
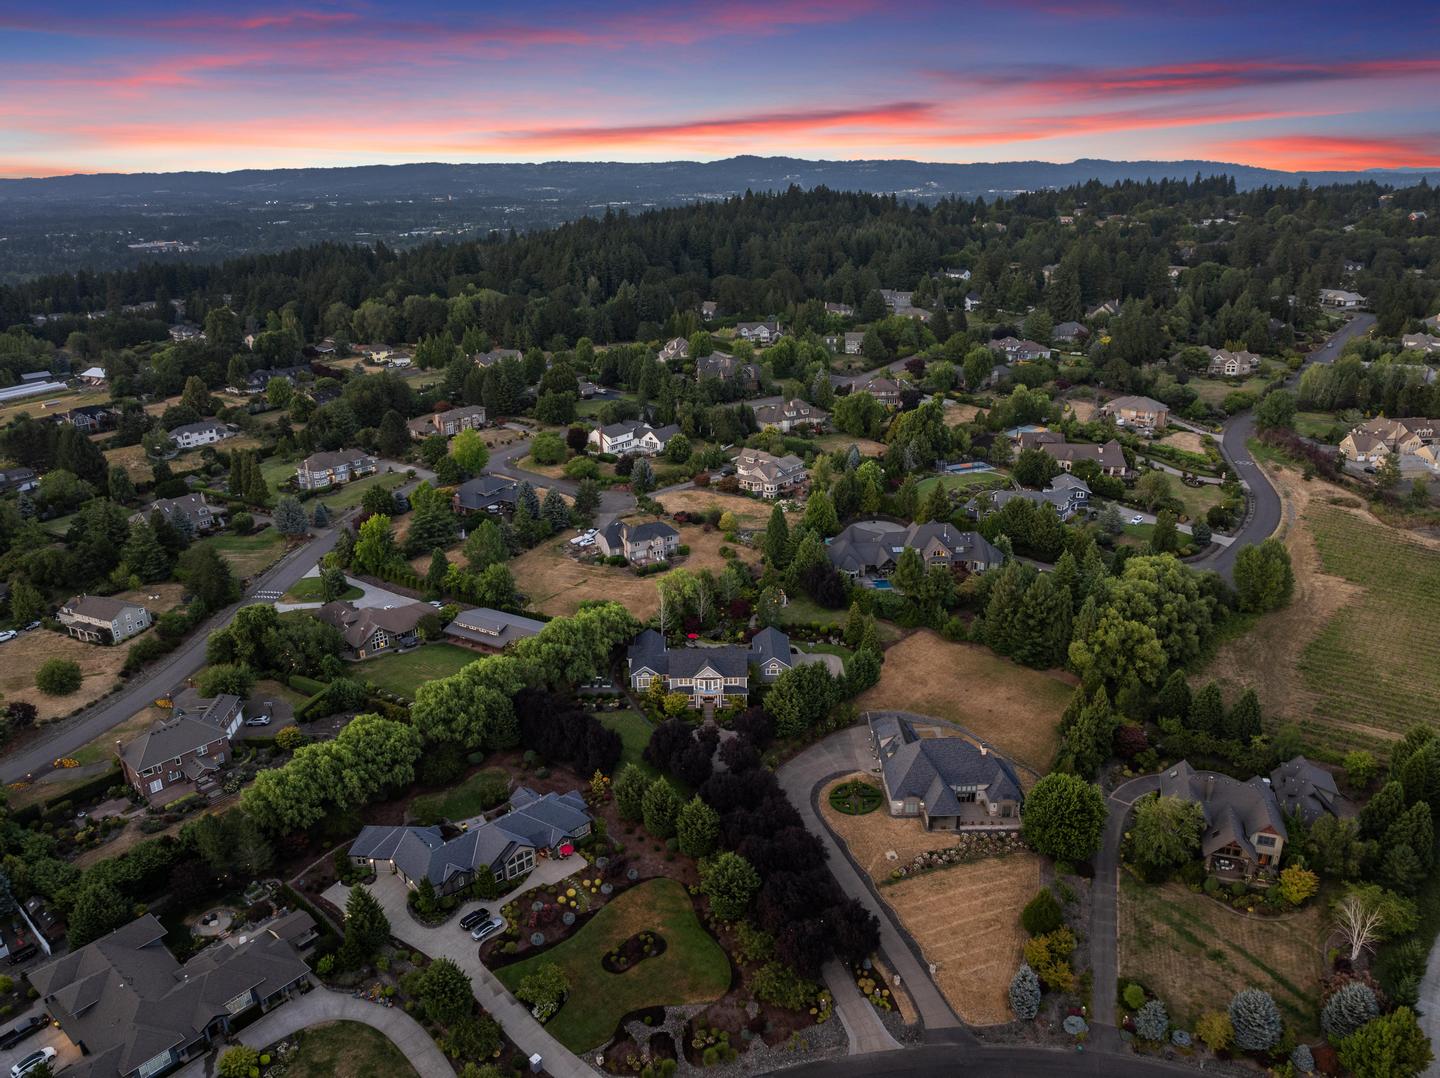
In the quiet suburbs of Beaverton, Oregon, a cautious real estate market is offering opportunities that buyers may be overlooking in their focus on interest rates. According to Carey Hughes, Principal Broker at Carey Hughes Homes, the prevailing anxiety about rates near 7% is keeping many prospective buyers on the sidelines, even as the market tilts in their favor for the first time in years.
"Cautious buyers are afraid of the interest rate, and so that is holding them back from even looking," Hughes says. "And this is a time where they actually have more opportunities." She describes current Beaverton conditions as balanced on paper but functionally buyer-friendly in practice. Inventory has expanded, sellers listing now often have a genuine need to move, and the multiple-offer bidding wars of two to three years ago have subsided. Sellers are offering concessions, including closing cost credits that can buy down interest rates, a rarity during the recent seller's market.
The very factor driving buyer hesitation—elevated rates—is also suppressing competition and creating negotiating leverage, Hughes explains. This dynamic is starkly different from hot markets like the Bay Area, where scarcity and bidding wars dominate. In Beaverton, buyers have time to make considered decisions and negotiate terms that could save them thousands upfront.
Hughes draws a crucial distinction between two variables buyers often conflate: the interest rate on a mortgage, which can be refinanced later, and the purchase price, which is permanent. "Rates are not forever, and your original purchase price is," she says. "The key point is to get in at a good price. That is the best way to set off your long-term investment." Entering during a period of low appreciation establishes a lower baseline, from which buyers benefit when the market accelerates. Those who wait for rates to fall may find that the same improvement brings competing buyers back, pushing prices up and erasing the monthly payment savings they anticipated.
Hughes points to a specific rate threshold she watches. "As soon as the interest rates adjust without the risk of war and inflation, buyers are going to come back when they're closer to six or six and a quarter," she says. "That's a threshold we see. And then the prices start appreciating." For buyers who act now, that appreciation would represent equity gained from a lower entry point. For those who wait, it could mean higher prices that offset any rate benefit.
Hughes does not predict a market collapse, nor does she suggest a closing window measured in weeks. Her point is structural: a market without aggressive price appreciation is precisely when buyers build equity advantage. "The bottom is not falling out in real estate in any way," she asserts. "We have a very stable market, but there's an opportunity where price appreciation is not aggressively happening. And this is when you get ahead as a buyer."
Monthly affordability remains a real constraint, and Hughes acknowledges the challenge. Yet she argues that treating rate levels as a binary go/no-go signal is a strategic error, ignoring the price and negotiation environment that elevated rates have created. In a hot market like the Bay, waiting rarely rewards patience; in Beaverton, it may cost more than it saves.
For buyers ready to act, Hughes recommends practical steps: connect with an agent who knows local neighborhoods, schools, and commuter routes, and get pre-approved before touring homes. Pre-approval sets a realistic budget and positions buyers to act when the right property appears. She also suggests touring six to eight homes across different neighborhoods and price levels in a single afternoon to build a frame of reference, so that when the right property appears, buyers recognize it immediately.
Negotiation can yield tangible results. "Negotiation can bring adjustments in price. It can bring closing cost credits to help buyers buy down the interest rate so they can get better affordability," Hughes notes. "If the home's been on the market for a while, you can get some help from the seller."
If rates do fall toward the six percent range Hughes identifies as a tipping point, buyer competition will likely return, and today's negotiating leverage will disappear. Buyers who act now can lock in lower purchase prices—the one number in the transaction that cannot be changed later. As Hughes summarizes, the current market offers a window of opportunity that may not last.