
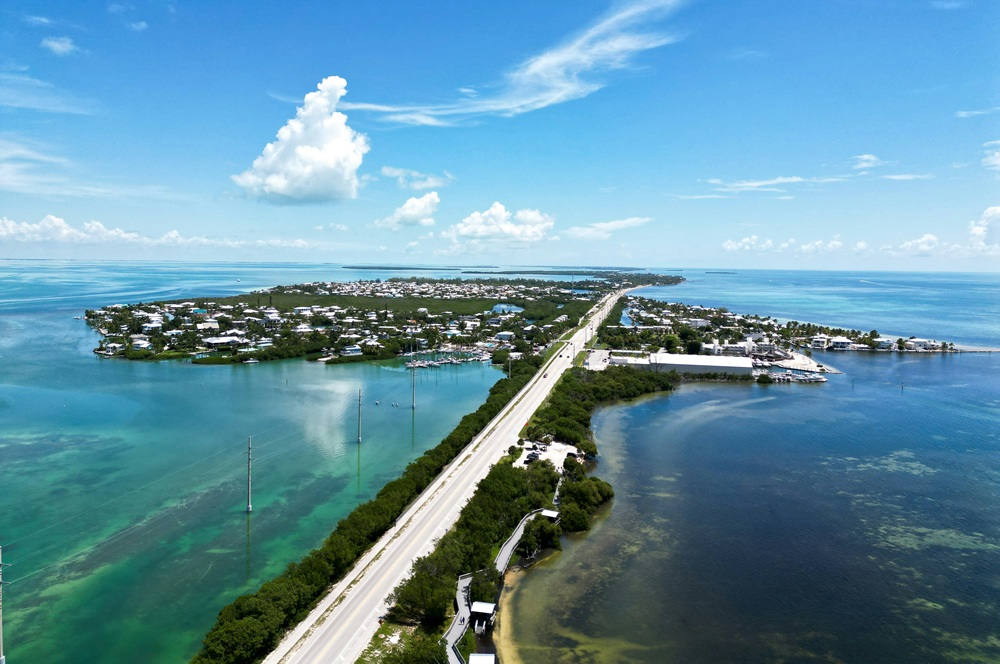
In the Florida Keys, aggregate price figures are painting a picture that matches almost no one's actual experience. A handful of record-breaking sales at the top of the market have skewed averages and medians upward, while a larger segment of older canal homes has been steadily declining in value. When averaged together, these two divergent trends produce a single number that misrepresents both ends of the spectrum.
Sandy Tuttle, founder of Island Welcome Real Estate, works primarily in unincorporated Monroe County in the Lower Florida Keys. She sees the disconnect from both sides and notes that interpreting the current statistics is one of the hardest tasks for out-of-state buyers without local context.
Historically, the Florida Keys housing stock was remarkably uniform. The islands attracted fishermen and weekend boaters, and the properties reflected that lifestyle. For decades, the average home size hovered near 1,000 square feet, and two-bedroom, two-bathroom layouts dominated. Large vacation estates were virtually nonexistent.
That began to change over the past decade. New construction has introduced homes ranging from 4,000 to 10,000 square feet, built to modern code with wind ratings exceeding 180 miles per hour. These are not merely larger houses; they represent an entirely new product category that previously did not exist in the region.
As this upscale inventory has started to trade, it has produced transaction prices with no historical precedent. Tuttle points to single-family sales in the Lower Keys at $12 million and $13 million within the past five years. Islamorada has recorded sales in the $20 million to $22 million range over the last year. "We are constantly crushing ceilings that the Florida Keys have always had," Tuttle said.
These high-end transactions are a genuine and growing part of the market, but they are statistically disruptive when the dominant average sale price hovers around $1.5 million. A few eight-figure closings can materially shift the mean and median for the entire island chain, which is then reported as market-wide appreciation.
Beneath that surface, conditions are starkly different. Canal homes priced under $1 million are mostly 1980s and 1990s construction, featuring smaller two-bedroom layouts built to earlier code. Inventory in this segment is high, buyer demand is comparatively soft, and competition among sellers has driven real price corrections rather than appreciation. "You cannot talk to that seller and tell them the market moved five to seven percent last year," Tuttle said. Days on market in this segment run substantially longer than the reported average, though for different reasons than at the top, where the buyer pool is simply smaller.
The practical consequence is that consumer-facing valuation tools, which apply a broad price-per-square-foot methodology across the chain, often produce misleading output. A seller in the sub-million-dollar canal band might read a headline appreciation figure and price their home accordingly. A buyer in the same band might assume they are entering a rapidly rising market, when in fact values are softening.
Tuttle's approach is to strip the analysis down to the price range the client is actually operating in, then examine absorption, days on market, and pricing behavior within that specific band. Sellers whose properties fall outside the current high-demand profile are counseled on realistic positioning. Buyers are shown where pricing is aggressive, fair, or inflated relative to comparable inventory in their range, rather than relative to the market as a whole.
As older ground-level stock continues to be converted to new construction, the spread between these two segments is likely to widen further before it narrows. That will make chain-wide averages even less useful as a guide for individual transactions.